What is the scope and industry significance of the Metal Fabrication Market?
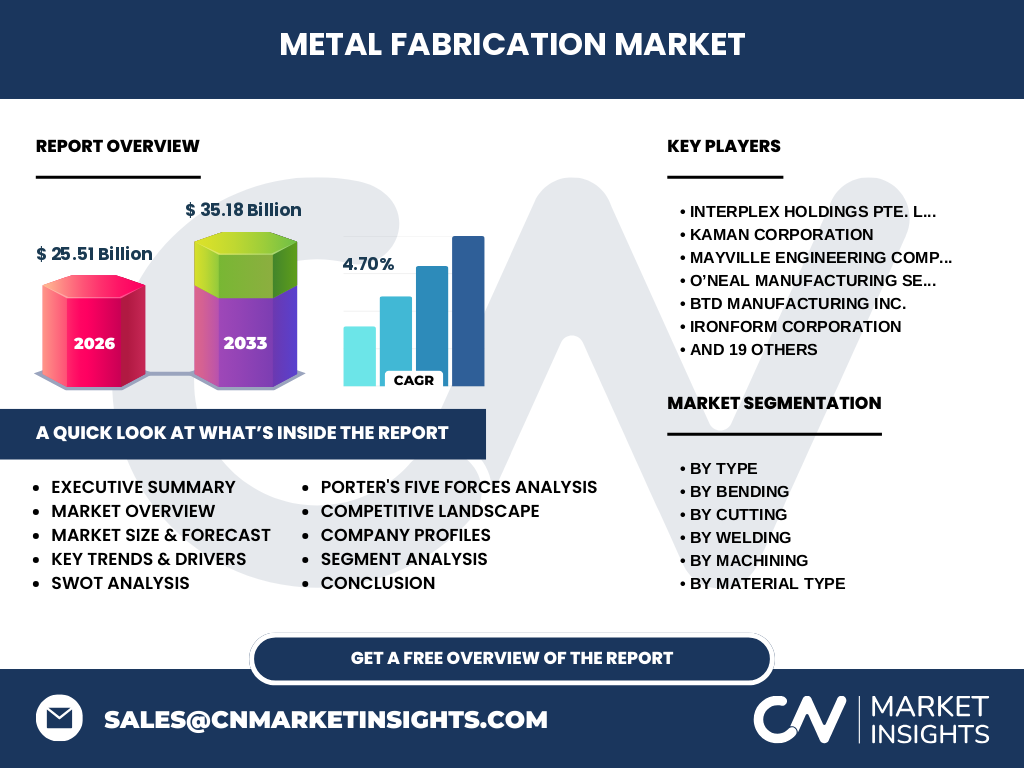
Our analysis indicates that the Metal Fabrication Market is valued at $25.51 Billion in 2026, serving as the foundational backbone for global infrastructure, automotive, and energy sectors. This sector encompasses complex processing of raw materials like steel and aluminum through cutting, machining, welding, and bending to deliver mission-critical components for heavy industry.
Structural Growth Drivers and Market Restraints
The market is propelled by robust infrastructure investments across emerging economies and advanced automation adoption. Based on our research, growth is restrained by volatile raw material pricing in steel and aluminum, alongside stringent OSHA and ISO compliance burdens that increase operational overhead for tier-two fabricators.
The Shift Toward Automated Precision in Metal Fabrication Industry Trends
Industry trends reveal a decisive migration toward CNC bending, laser cutting, and robotic TIG welding. This technological shift addresses acute skilled labor shortages while dramatically tightening geometric tolerances for aerospace and energy clients demanding flawless repeatability.
How did the COVID-19 pandemic impact the Metal Fabrication Market recovery trajectory?
The pandemic caused severe supply chain fractures and temporary factory lockdowns across major industrial hubs. However, the post-crisis recovery trajectory has been robust, driven by automated shop-floor upgrades and reshoring initiatives by firms like Mayville Engineering Co. Inc. to mitigate offshore logistical bottlenecks.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains moderately fragmented, featuring agile regional specialists alongside diversified industrial giants. Competitive positioning heavily relies on proprietary welding certifications, multi-axis laser cutting capabilities, and end-to-end vertical integration managed by key participants such as Interplex Holdings Pte. Ltd. and Kaman Corporation.
Executive Summary of Metal Fabrication Market Findings
Our executive synthesis highlights a projected market expansion from $25.51 Billion in 2026 to $35.18 Billion by 2033 at a steady 4.70% CAGR. Success in this landscape increasingly demands digital transformation, lean manufacturing, and advanced metallurgical expertise in high-strength aluminum and alloyed steel.
Long-Term Market Forecast from 2027 to 2033
The data suggests the sector will expand from $25.51 Billion to reach $35.18 Billion by 2033, expanding at a compound annual growth rate of 4.70%. This trajectory is underpinned by rising power generation and utilities demand requiring heavy plate rolling and specialized submerged arc welding.
Comprehensive Segmentation Analysis
The market is systematically categorized by type (cutting, machining, welding, bending), material type (steel, aluminum, other materials), and end-use industry (manufacturing, power and utilities, construction, oil and gas). Each segment addresses unique technical tolerances, with laser cutting and CNC machining driving high-margin precision applications.
Geographic Distribution and Regional Market Analysis
Regional performance varies significantly, with North America and Europe prioritizing automated, high-precision machining, while Asia-Pacific dominates sheer volume output due to massive construction and manufacturing demand. Localized regulatory frameworks heavily dictate environmental filtration standards across these distinct operating theaters.
In-Depth Regional Review of Industrial Hubs
Industrial centers in North America leverage advanced robotics to offset high labor costs, whereas European fabrication shops focus heavily on eco-compliance and specialized alloy processing. Key players like O'Neal Manufacturing Services and BTD Manufacturing Inc. anchor regional supply chains through strategic geographic positioning near major logistics corridors.
Strategic Positioning in Company Profiles
Leading entities utilize specialized geographic footprints and technological specialization to secure enterprise contracts. Firms like Kapco Metal Stamping and CGI Automated Manufacturing leverage high-speed turret presses and automated press brakes to dominate high-volume stamping and complex weldment assemblies.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate to high due to numerous regional metal service centers, while threat of substitutes is low given metal's structural superiority. Rivalry is intense, forcing fabricators to invest continuously in automated fiber lasers and advanced robotic welding cells to protect operating margins.
SWOT Analysis of the Metal Fabrication Sector
Key strengths include deep engineering expertise and versatile material handling, balanced by weaknesses in raw material price exposure. Opportunities abound in renewable energy infrastructure components, though persistent threats stem from geopolitical trade tariffs on imported steel and tightening environmental emissions mandates.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from primary steel mills and aluminum producers through intermediate service centers, specialized fabricators like Hartwell Manufacturing or Watson Engineering Inc., and finally to OEMs in construction and oil and gas. Value creation peaks during complex assembly and certified welding stages.
Investment Insights and High-Potential Areas
High-potential capital allocation targets automated robotic welding cells, greenfield fiber laser cutting lines, and proprietary software integration for shop-floor IoT. Investors should favor tier-one suppliers possessing diversified end-market exposure across both power and utilities and advanced manufacturing.
Conclusion and Strategic Takeaways
The Metal Fabrication Market represents a resilient, evolving sector poised to reach $35.18 Billion by 2033. Long-term viability depends on adopting advanced automation in cutting and bending while proactively navigating raw material volatility and skilled labor deficits.
Rigorous Research Methodology for Baseline Estimates
Our analysis is triangulated by combining primary executive interviews with shop-floor plant managers, official trade registry statistics from international steel institutes, and secondary macroeconomic indicators tracking global industrial capital expenditure and purchasing managers' indices.
Scope of the Report and Coverage Parameters
This report evaluates the global Metal Fabrication Market industry trends across specified cutting, welding, bending, and machining typologies from 2026 through 2033. Exclusions apply to captive in-house fabrication lines that do not participate in merchant commercial contracting.
Recent Developments and Strategic Industry Moves
Recent market dynamism includes aggressive capital expenditure in high-power fiber lasers by players like Schaumburg Specialties LLC and strategic facility expansions by Adey Steel Ltd. These moves reflect a broader industry push toward lights-out manufacturing and reduced cycle times.